Discover programs & events in your region
New Energy Nexus programs
Programs we run with our partners
A new strategy and action plan outlines how the region can turn its industrial legacy into a high-road clean energy future.
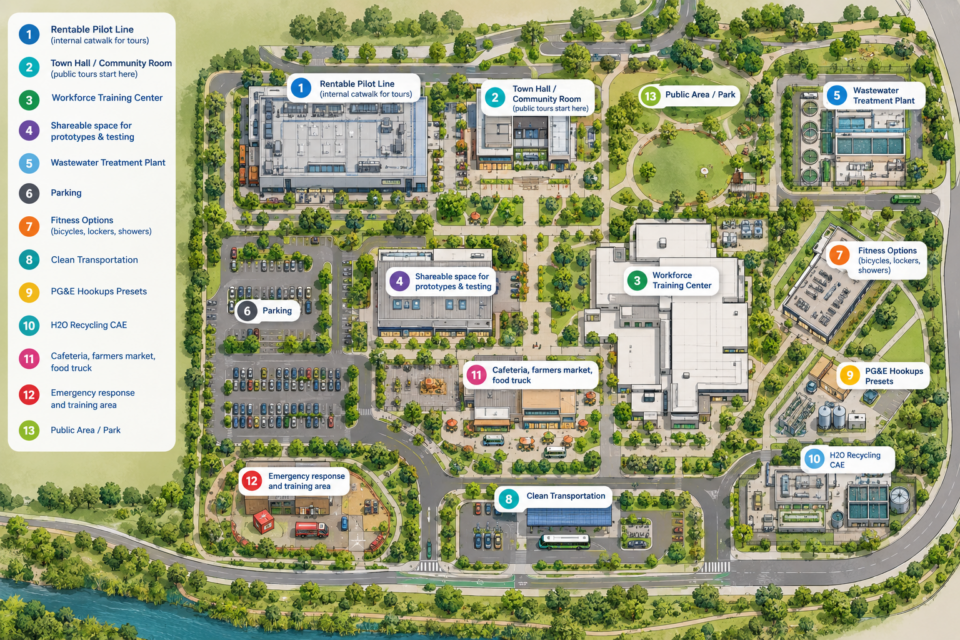
Contra Costa county high road battery innovation hub mockup
California is a world leader in battery innovation. From cutting-edge research at UC Berkeley and Lawrence Berkeley National Laboratory to a thriving startup ecosystem, the state has all the ingredients to lead the global energy transition. Yet too often, the technologies invented here are manufactured somewhere else—taking jobs, supply chains, and long-term economic value with them.
A new report aims to change that. “Contra Costa County: High-Road Battery Innovation Hub Strategy and Action Plan” presents a comprehensive strategy to establish the region as California’s premier destination for midstream battery manufacturing, and to do it in a way that protects workers, communities, and the environment.
Contra Costa County has been the Bay Area’s industrial heart for more than a century. As California decarbonizes, the region’s skilled workforce, existing industrial infrastructure, and proximity to ports, highways, and world-class research institutions make it uniquely positioned to lead the next generation of advanced manufacturing.
The report, developed by New Energy Nexus and the UC Berkeley Labor Center in collaboration with the Contra Costa High-Road Battery Roundtable, outlines a vision that builds on the region’s strengths rather than replacing them.
At its core, the High-Road Battery Innovation Hub is about growing the battery industry as a race to the top, not a race to the bottom. That means:
Quality jobs with strong worker voice and career pathways
Environmental protection and community health safeguards
Durable public benefits from public investment
Shared prosperity for workers, employers, and communities
Rather than asking individual companies to overcome permitting, infrastructure, and workforce barriers alone, the Hub proactively addresses these challenges through built-in partnerships with government, labor, education, and community organizations.
The global lithium-ion battery market exceeded $150 billion in 2025, driven by electric vehicles, grid-scale storage, data centers, and industrial electrification. While China currently dominates battery manufacturing, the U.S. has a strategic imperative to build domestic supply chains, and California has a unique opportunity to capture the midstream segments where innovation strengths are highest and domestic capacity remains limited.
The report identifies critical materials processing, battery components, and pilot-scale manufacturing as target areas where Contra Costa can fill gaps in the U.S. battery ecosystem.
The strategy was developed through an 8-month collaborative process that brought together manufacturers, labor organizations, community groups, environmental advocates, workforce organizations, educators, and government agencies. The result is a roadmap that is grounded in real employer needs, data-driven analysis, and community input.
The Implementation Roadmap outlines five phases, from research and planning to building, deploying, and scaling, over the next several years.
The Contra Costa High-Road Battery Innovation Hub represents a once-in-a-generation opportunity to build a cleaner, more equitable, and more resilient economy. But it won’t happen automatically. It will require coordinated public and private investment, sustained commitment from partners across sectors, and a shared vision for what advanced manufacturing can look like when it puts workers and communities first.
The Contra Costa County: High-Road Battery Innovation Hub Strategy and Action Plan was prepared by Areana Flores of New Energy Nexus. Financial support for convening participants and preparing this report was made possible by the Bay Area High Road Manufacturing Initiative, through a grant from California Jobs First.
Australia’s Anodean and Vietnam’s Volterra win first Supercharge Australia Innovation Challenge open to Southeast Asia
Melbourne, 28 October 2026 – Startups backed by Supercharge Australia, the battery startup program run by New Energy Nexus and EnergyLab, have raised AU$212 million since joining and now work at every stage of the battery value chain, from minerals and materials to cells, packs, end uses and recycling.
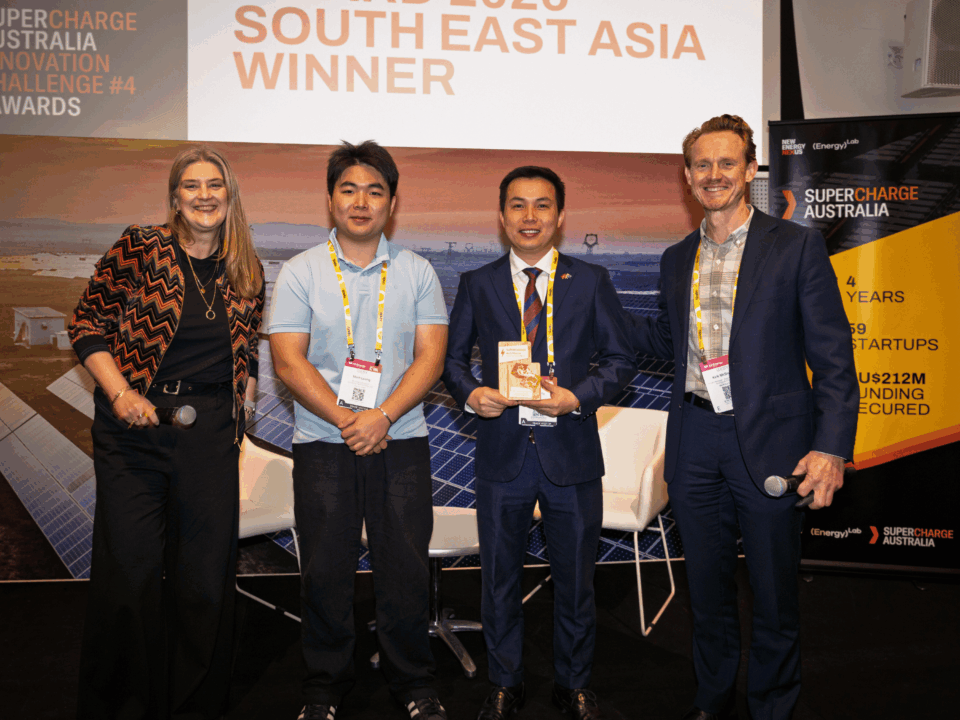
Australian solid-state lithium ion battery startup Anodean wins Supercharge Australia Innovation Challenge #4
The two organizations published the findings today in Closing the Loop, an analysis of the program’s 59 startups, at All Energy Australia in Melbourne. At the same event, solid-state battery cell developer Anodean and Vietnam’s Volterra were named winners of the 2026 Supercharge Australia Innovation Challenge, the first cohort open to startups from Southeast Asia.
Closing the Loop maps where the program’s 59 startups work along the battery value chain, how much they have raised since joining, and how far recycling could reduce the world’s need for new mines. Key insights from the data:
Australia mined about a third of the world’s lithium in 2025, more than any other country, according to the United States Geological Survey. It is also close to Southeast Asia, which the International Energy Agency expects to account for a quarter of global energy demand growth to 2035, second only to India. Battery investment already moves between the two: Brisbane-based StB Capital Partners funded the Philippines’ first lithium iron phosphate battery factory, which opened in 2024 with plans to export most of its output, including to Australia.
“Australia produces a large share of the world’s lithium and captures a fraction of the value it creates further down the chain. This year’s founders are refining lithium, making battery materials and developing new cells in Australia, and with founders from Southeast Asia now in the program, we are building that capability alongside neighbors who are growing battery and electric vehicle industries of their own,” said Kirk McDonald, Project Manager, Supercharge Australia.
“Minerals, battery materials, and cells are the most challenging and capital-intensive parts of the battery value chain, but they are also where Australia builds genuine sovereign capability, long-term energy security and economic productivity. We are seeing incredible ambition from founders stepping into these complex stages. To help them reach commercial scale and anchor those high-value supply chains locally, they need patient investment, early pilot customers, and simplified access to capital,” said Megan Fisher, Chief Executive Officer, EnergyLab.
This year’s Innovation Challenge was the program’s first cross-border round. Anodean, which is commercializing solid-state battery cells with double the energy density and lower capital costs for new production, was named best Australian startup and wins guided market entry and a funded visit to Southeast Asia.
Volterra, from Vietnam, builds energy management software for electric vehicle charging networks that matches demand to available supply, raising efficiency and throughput. It was named best Southeast Asian startup and wins the same support to enter Australia. Both prizes are delivered through New Energy Nexus programs in Indonesia, Thailand, Vietnam and the Philippines.
“Winning the Supercharge Australia Innovation Challenge is a huge boost for our team and gives us the backing to take Anodean to the next stage. Our technology has the potential to enable a generational leap for mobility applications in mining and long haul transport here in Australia. The opportunity to expand in Southeast Asia will also opens doors to new partners and customers, enabling us to scale in one of the fastest growing regions globally,” said Swaroop Tulsidas, CEO at Anodean.
“Winning means a great deal to our team and gives Volterra a real opportunity to grow beyond Vietnam. The support to enter Australia will help us build new partnerships and reach new customers, and we look forward to bringing our technology to the Australian market,” said To Lang, CEO, Volterra.
Verdant Ion, aiming to grow the world’s graphite battery anodes by converting oils to graphene and then to battery grade graphite won the People’s Choice award.
“Winning the People’s Choice Award validates our belief that the only way to solve the world’s impending massive deficit in battery anodes is to grow it. We’ve already scaled literally a billion-fold from our first nanoscale lab success. We’ll grow anodes in Australia, South East Asia, and beyond,” said Tim van der Laan, CEO at Verdant Ion.
Closing the Loop, including the startup dashboard, recycling projection and methodology, is available here.
About EnergyLab
EnergyLab is Australia’s largest climate tech startup accelerator and innovation network, backing founders who are building the technologies that will accelerate the transition to net zero. With more than 350 startup alumni, EnergyLab connects entrepreneurs with the mentors, partners, and investors they need to grow and scale. Each year, EnergyLab delivers ten programs that support founders at every stage of development – from ideation and launch to global expansion – helping position Australia as a leader in clean energy and climate innovation.
Kirk McDonald
Project Manager, Supercharge Australia
kirk.mcdonald@newenergynexus.com
Tristan Tremschnig
Chief Communications Officer, New Energy Nexus (based in Hong Kong)
tristan.tremschnig@newenergynexus.com
About New Energy Nexus
New Energy Nexus (NEX) is the world’s leading clean energy ecosystem builder, working toward a 100% clean energy economy for 100% of the population. It does this with a laser focus on diverse entrepreneurs, supporting them with accelerators, funds, skills, and building the local and global connections they need to thrive. NEX has accelerated 1,700+ startups and businesses, empowered over 11,500+ entrepreneurs, and mobilized more than US$5.4 billion in investment.
Since its founding in California in 2004, NEX now operates programs or services in Australia, China, India, Japan, Indonesia, Nigeria, Pakistan, the Philippines, South Korea, Thailand, Uganda, the USA (California and New York), and Vietnam.

Snow covered street in Saporro, Japan
Sapporo is the snowiest major city in the world, and clearing it is expensive. Hokkaido’s cities spend on the order of ¥100 billion (~US$630 million) a year on snow management, using diesel trucks and manual labor, and across 12 cities in the region those costs have risen 1.8 times in a decade. None of this appears in Japan’s national decarbonization strategy, yet it is the problem Sapporo City wants solved, and it is the opening our Japan team has used to bring climate tech onto the table.
That is how subnational work tends to start. The national target sets a direction, and the region supplies the problem worth solving, the site to test on and the budget already being spent. Our teams in Japan, South Korea, China and California all described a version of it in this webinar.
All 17 of Korea’s major regions now have carbon neutrality and green growth plans, under a national target of roughly 40% emissions reduction by 2030. The interesting part is what the regions do with that mandate. Gyeonggi is building around industrial solar, corporate PPAs and climate tech startups. Seoul focuses on retrofits, efficiency and electrification. Jeollanam-do works on offshore wind and ocean energy. As Minsoo Chung, our Korea Program Lead, put it:
“Korea’s provinces and cities are becoming more than administrators of climate policy. They are becoming market makers, customers, ecosystem builders and testing grounds for the next generation of climate technology.”
China’s local governments have run most of their early clean energy policy through industrial parks and economic zones, testing subsidies and rules inside a small area before applying them more widely. Goldwind, now the country’s largest wind turbine maker, was founded in Urumqi in 1998 and built its early business from the city’s economic and technological development zone, where Shane says land, rent and tax terms were part of what let it scale. After listing in Shenzhen in 2007, it moved to a development zone in Beijing, and grew again from there. Two decades of Chinese manufacturing strength were assembled one zone at a time.
Hokkaido has been designated a GX financial zone (a national strategic special zone designated to drive Green Transformation), and our Japan team, led by Huong Ly-Le, has been working with Sapporo City to find where global climate tech can play a role. The answer was snow (yep, snow!). Sapporo gets up to five meters of it a year, and snow management costs the region on the order of ¥100 billion annually. Removal is diesel-and labor-intensive, and across 12 Hokkaido cities have risen 1.8 times in a decade. Treating snow as a resource for data center cooling and thermal storage turns a municipal expense into an innovation agenda.
California’s clean tech pipeline was built on public funding. CalSEED has awarded grants of up to US$700,000 to 158 startups, and CalTestBed vouchers have given 67 startups access to third-party testing across nine University of California campuses and Lawrence Berkeley National Laboratory. That pipeline produced companies like Gridware, founded by a former lineman with no route into the venture community, which now has more than 1,000 wildfire detection units deployed across PG&E territory since 2020. Joy Larson, our California Program Director, was blunt about what comes next:
“Government funding has just gone off a cliff. That’s an opportunity for non-governmental money to support subnational work towards energy transition.”
Subnational regions solving these problems rarely talk to each other. Our China team hosted delegations from Pakistan and Thailand during Shanghai Climate Week and took an EU Commission group through a Shanghai development zone, and in each case the questions were about things China worked out years ago inside its industrial parks. Korean startups from Gyeonggi went the other way, to Boston Climate Week, looking for customers and capital.
The opportunity is to connect these places more deliberately, so that a technology Hokkaido needs to tackle its snow challenge, for example, can be found in Korea or the United States rather than developed from scratch. There is still surprisingly little cross-pollination between these clean energy innovation ecosystems, and working at the subnational level also creates a way to keep moving when national ambition stalls.
If you’re a funder, corporate or regional agency and want to find out more, talk to us.
Watch the full webinar recording:

California is a leader in battery innovation, research, and talent development. To build a resilient clean energy transition and capture the full economic benefits of this growing industry, the state also needs a diverse, domestic battery supply chain that spans the entire value chain—including manufacturing. Yet despite its leadership in innovation, California continues to lose large-scale manufacturing investment to other regions and states.
A new employer assessment brief from New Energy Nexus California reveals why the State struggles to attract battery manufacturers compared to other states and what the state can do to compete. The findings are clear: structural barriers hold back companies willing to invest and scale production locally.
Manufacturing siting decisions depend on speed, certainty, and cost. California scores high on talent and innovation but falls short on:
When regions compete for manufacturers, speed makes all the difference. Companies compare regions primarily on how quickly they can start operating. Speed and certainty outweigh small cost differences.
The Bay Area High Road Manufacturing Initiative (BAHRMI) is leading the effort to transform how manufacturing investments and workforce resources are deployed across the region. BAHRMI unites industry, labor, and community partners to build an inclusive, competitive, and sustainable advanced energy manufacturing economy for the Bay Area.
BAHRMI is actively developing pilot projects in Contra Costa County to cultivate high-road battery manufacturing, engaging employers, labor unions, workforce development partners, government, and community stakeholders to design a high-road battery innovation hub that creates quality jobs and builds community wealth.
The assessment identifies eight recommendations that could reduce uncertainty, lower costs, and speed timelines for manufacturers. These align directly with BAHRMI’s high-road approach.
California has the talent, innovation, and market demand. What it lacks is the coordinated strategy to turn these assets into manufacturing growth. By investing in pre-permitted sites, shared infrastructure, targeted incentives, and a skilled workforce guided by high-road principles, the Bay Area can become a hub for advanced battery manufacturing that creates good jobs, strengthens regional competitiveness, and supports long-term economic and energy affordability goals.
Download the full employer assessment brief for detailed findings and recommendations.
The employer assessment brief was prepared by Areana Flores of New Energy Nexus. Financial support for convening participants and preparing this report was made possible by the Bay Area High Road Manufacturing Initiative, through a grant from California Jobs First.
For updates related to this report, follow BAHRMI’s LinkedIn here.
For questions, reach out to Areana Flores at areana.flores@newenergynexus.com
Written by Jennifer Wang, Director of Financial Innovation at New Energy Nexus
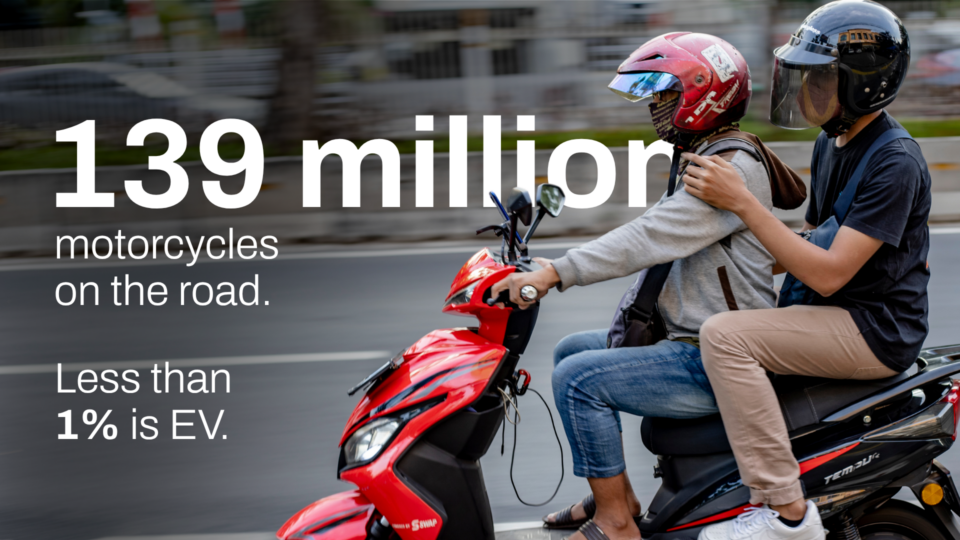
Anyone who lives in or has visited Jakarta will have seen the motorcycles: slipping between cars, gathering at intersections, carrying passengers, food orders, parcels, tools, and stock for small businesses. They are often treated as part of the traffic problem, but in Indonesia they are the backbone of the transportation system. With around 139 million two-wheel vehicles on the road, Indonesia’s motorcycle market is the third largest in the world, but less than 1% of those are electric.
This is why the energy crisis is hitting Indonesians hard.
State-owned energy company Pertamina raised the price of its flagship Pertamax gasoline by more than 30 percent in June, from Rp12,300 to Rp16,250 a litre. This is causing consumers to take a hit to their personal income, or else switch to the lower grade government-subsidized Pertalite fuel, which some fear could cause long-term damage to their vehicles. Long queues have already been observed at many gas stations across the country, and there is no telling how long the government will be able to continue to shoulder the growing cost of subsidizing Pertalite, despite assurances from the energy minister.
The solution seems obvious: reduce the nation’s dependence on fossil fuels.
In fact, Indonesian President Prabowo Subianto has framed reducing dependence on imported fossil fuels as a strategic national priority and the country already has ambitious targets for EVs. But accelerating EV adoption, especially two-wheelers, will require a multipronged approach that includes policy and financial solutions.
For drivers, couriers, and low-to-middle income households, multiple barriers are holding back the switch to electric motorcycles. Government incentives have been inconsistent, with the 2023 purchase subsidy introduced and then withdrawn less than two years later. And consumers remain hesitant, wary of a technology that hasn’t yet earned their trust or proven its resale value.
Beyond that, the EV landscape is fragmented, dominated by over 65 young local brands rather than the household names like Honda and Yamaha that anchor the internal combustion engine (ICE) market. Upfront costs are higher than traditional ICE vehicles, with little affordable financing to bridge the gap, and the charging, swapping, and repair infrastructure that ICE riders take for granted is nascent and uneven for EVs — growing, but nowhere near the density or reliability riders need.
Adoption is lagging
Electric motorcycles are already cheaper to operate: according to think tank RMI, the total cost of ownership of an electric motorcycle is at least 34% lower than an equivalent ICE vehicle, freeing up income for food, school, utilities, and other household needs.
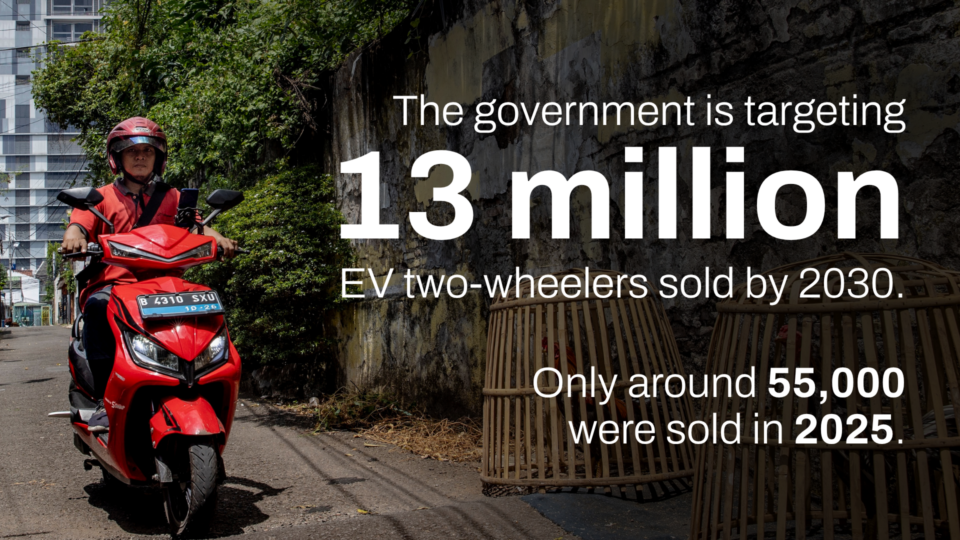
Yet adoption remains far below its potential, with electric motorcycles accounting for fewer than 230,000 units, or less than 1% of the total fleet. Annual electric motorcycle sales reached only around 55,000 units in 2025, less than 1% of new motorcycle sales.
The gap between ambition and reality is also striking. The previous administration set a target of 13 million electric motorcycles on Indonesian roads by 2030, but even optimistic industry projections put annual electric motorcycle sales at around 1.9 million by 2030.
Electric motorcycles, despite representing arguably the strongest energy security opportunity, have received comparatively less policy attention. Responsibility for the EV transition is split across the energy, industry, finance, and transport ministries, and coordination among them has remained weak, with no single institution effectively driving it. Indeed, much of Indonesia’s recent EV momentum has centered upstream, on nickel mining and processing – of which Indonesia is the producer for the world – and battery materials.
Financial barriers to adoption
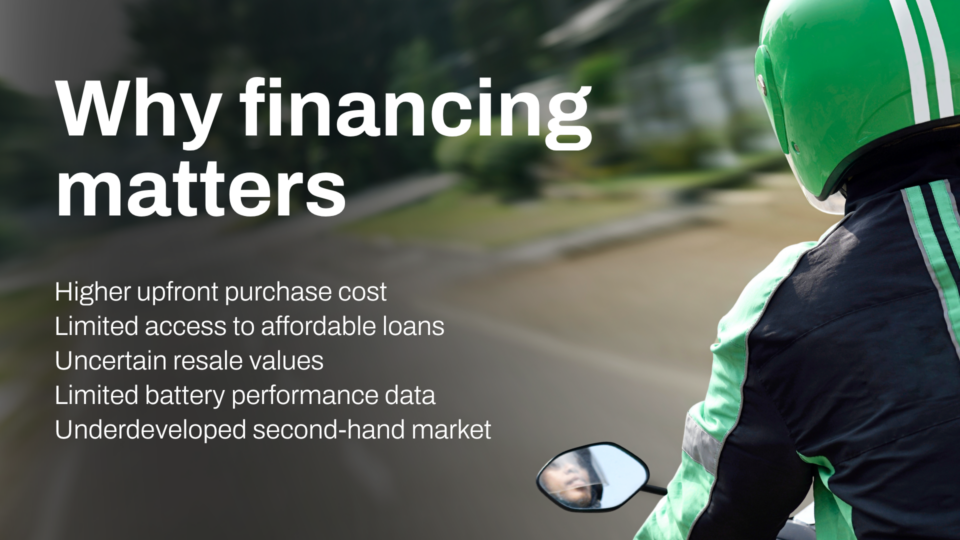
Policy, however, only gets us so far. The biggest barrier for consumers is the high upfront cost. Electric motorcycles remain approximately Rp5-6 million (US$280 to US$336) more expensive than comparable conventional motorcycles and financing is one of the most significant obstacles to wider adoption.
While around 80-90% of conventional motorcycle purchases in Indonesia are financed according to our own stakeholder interviews, only a small fraction of electric motorcycle buyers currently access the formal lending market. Where loans are available, the terms are often less favorable than those offered for conventional motorcycles.
Furthermore, as households come under financial pressure, consumers often delay major purchases, including vehicles. This creates an important challenge for the EV transition. Even if electric vehicles offer lower operating costs over the long term, their upfront cost can remain out of reach for many households, particularly when there is not a robust secondary market that could give consumers comfort that they can quickly sell their vehicle for cash if financial pressures mount. This reality highlights why affordability matters just as much as technology.
These conditions reflect legitimate concerns among lenders, too. Electric motorcycles are still a relatively new asset class, with limited data on battery performance, resale value, and long-term reliability.
The same concern that consumers have about being able to liquidate their vehicles in a pinch also affects lenders and the residual value they would receive for the vehicle if it had to be repossessed. The fragmented EV landscape and less developed after-sales market also increase the risk that a borrower would be unable to make payments on the loan if a faulty vehicle prevents the driver from utilizing it for their livelihood. The result is that financing often becomes inaccessible for the very consumers who stand to benefit most from lower operating costs, particularly ride-hailing drivers, delivery workers, and low-to-middle income households.
The solutions that need scaling
Several Indonesian companies are experimenting with financing models designed specifically for the realities of the country’s motorcycle market.
One example is Indonesian EV startup’s Cocoride platform, which combines battery-swapping infrastructure with rent-to-own financing and provides drivers with access to electric motorcycles without many of the barriers associated with conventional vehicle loans. Through daily repayment structures, remote monitoring technology, and rapid vehicle redeployment, the model is designed around the realities of Indonesia’s informal and platform-based workforce. Along with Cocoride, there are a handful of other innovative financing structures being deployed (Electrum, Aizen, and Blitz Electric Mobility are just a few) that help these livelihood drivers access the significant benefits of driving and owning an electric motorcycle.
What these innovations have in common is an understanding that the challenge is not simply selling electric motorcycles. It is designing financial products and support systems that match how Indonesians actually earn, spend, and use transportation assets.
This is also where new policy and financing solutions can play an important role. Across emerging markets, governments, financiers, and development institutions are increasingly exploring tools such as guarantee facilities, blended finance structures, and risk-sharing mechanisms that can reduce lender exposure and unlock private capital for electric mobility. Policy interventions are being designed to support this mobilization, as well as to align with countries’ domestic manufacturing and industrial policy goals.
The opportunity
The clean energy transition that protects Indonesia from the next geopolitical oil shock also builds a domestic industry, creates jobs in manufacturing and battery production, and lowers the cost of mobility for the millions of Indonesians whose livelihoods depend on two wheels.
To accelerate adoption, Indonesia will need coordinated solutions that reduce the initial financial burden on consumers and help get more electric motorcycles on the road to create a secondary market. New Energy Nexus and UC Davis’ Global South Center for Clean Transportation are exploring possible policy and financing solutions, such as fiscal and non-fiscal policy, blended finance schemes, consumer and lender education, and mobility-as-a-service schemes.
This moment of crisis creates an opening to supercharge a mass transition to EVs.
Not only will a transition to electric two-wheelers support Indonesia’s emissions reduction targets, it will also offer financial stability for the millions of Indonesians who rely on their motorcycles to support their livelihoods.